
How much should your NZ business keep in cash reserves?
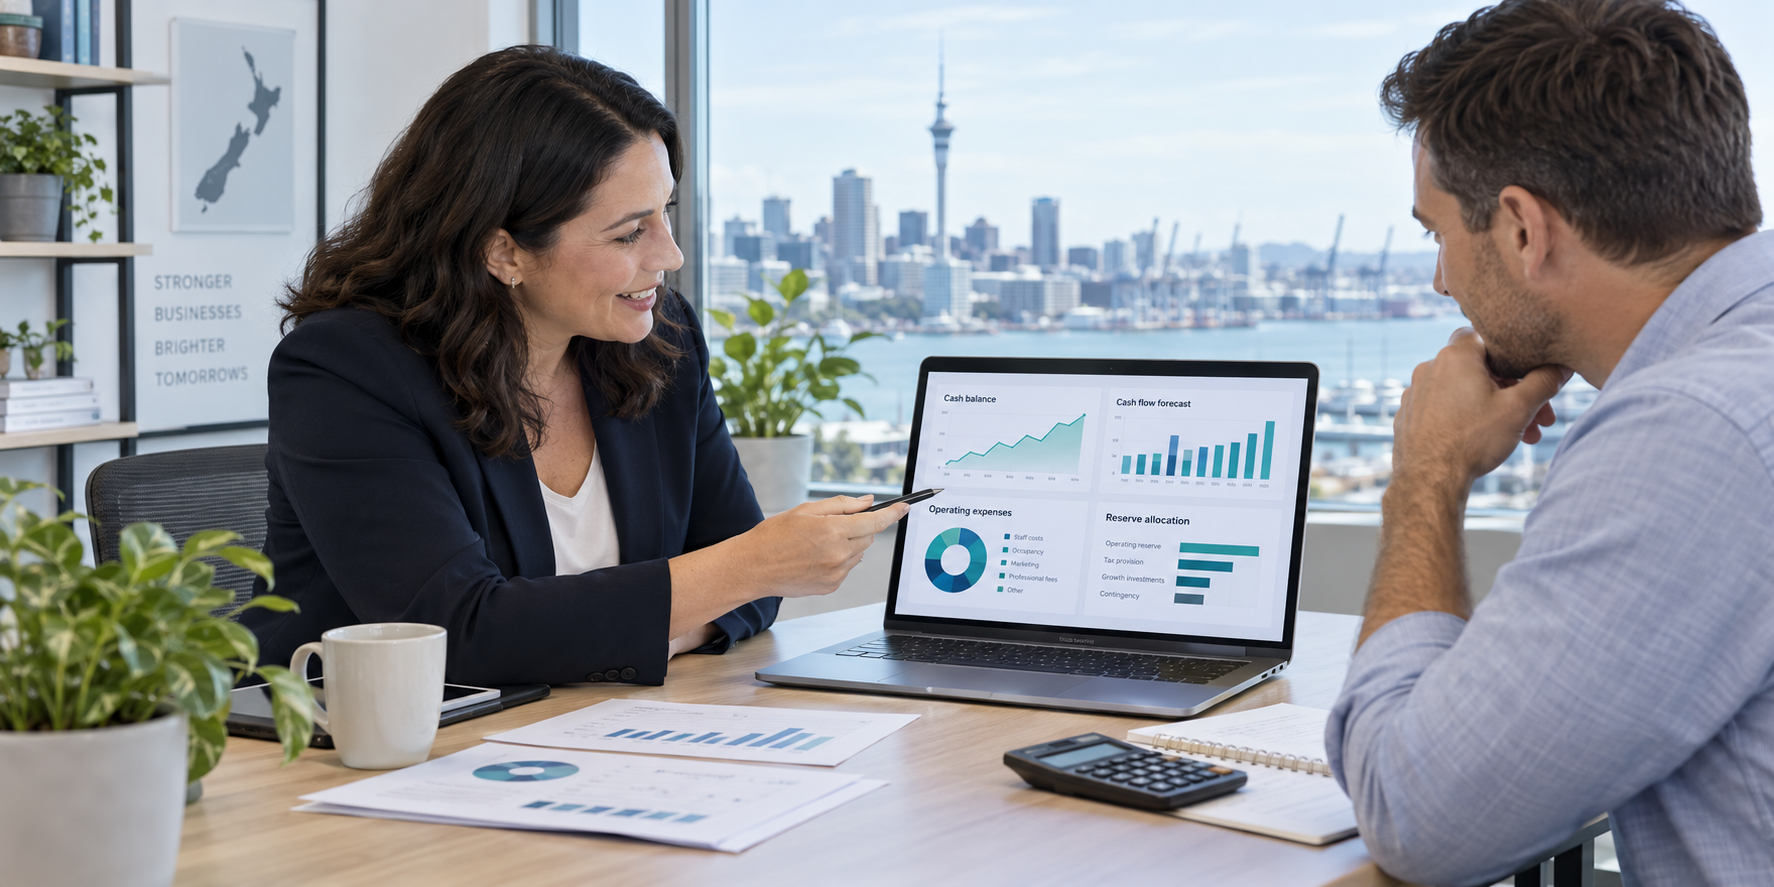
Having money in the bank can give a business owner confidence.
But how much cash should you actually keep available?
There is no single figure that works for every New Zealand business. The appropriate cash reserve depends on your industry, expenses, revenue stability, customer payment behaviour and financial commitments.
However, every business should have a plan for maintaining an appropriate level of cash reserves.
Why cash reserves matter
Cash reserves provide your business with a financial buffer.
They can help you manage unexpected situations such as:
A major customer paying late
A sudden equipment failure
Unexpected repairs
A downturn in sales
Higher operating costs
Staff-related expenses
Tax obligations
Emergency business expenses
Without cash reserves, even a temporary disruption can create significant stress.
Start by understanding your monthly expenses
Before deciding how much cash you need, calculate your essential monthly operating costs.
These could include:
Wages
Rent
Utilities
Insurance
Software
Vehicle expenses
Loan repayments
Supplier payments
Other unavoidable overheads
If your essential expenses total $50,000 per month, you have a very different cash requirement from a business whose essential expenses are $10,000 per month.
Don't confuse cash reserves with excess cash
Keeping cash available is important, but holding excessive amounts of idle cash may not always be the most effective strategy.
Business owners should consider what the cash is intended for.
For example, you may be building reserves for:
Working capital
Money required to operate the business.
Tax obligations
Funds set aside for GST, income tax or other obligations.
Planned investment
Money required for equipment, technology, premises or expansion.
Emergency reserves
A buffer for unexpected circumstances.
Having a specific purpose for your cash can make financial planning much easier.
Consider how predictable your revenue is
Not every business has the same level of financial risk.
A business with predictable recurring revenue may have different cash reserve requirements from a seasonal business.
For example, a subscription-based business may have relatively consistent monthly income.
A construction business may experience significant variations depending on project timing, progress payments and contracts.
A hospitality business may experience seasonal fluctuations.
Your cash reserve strategy should reflect the nature of your business.
What happens when a major customer doesn't pay?
Customer concentration is another important consideration.
If one or two customers represent a large percentage of your revenue, the business may be exposed if one of them delays payment or stops trading.
This is where cash reserves can provide valuable protection.
It is also why business owners should monitor:
Accounts receivable
Customer concentration
Payment terms
Overdue invoices
Credit risk
A strong sales pipeline does not necessarily mean strong cash flow.
Build reserves deliberately
Rather than simply hoping the bank balance grows, consider setting a specific cash reserve target.
For example, you might establish a policy that the business maintains enough readily available cash to cover a certain period of essential operating expenses.
The appropriate amount will depend on your business.
The important thing is to establish the target based on your actual financial circumstances rather than choosing an arbitrary number.
Review your reserves regularly
Your ideal cash reserve can change as the business changes.
You may need more cash when:
Hiring employees
Expanding premises
Taking on larger contracts
Purchasing equipment
Entering a new market
Experiencing rapid growth
You may also need to reconsider your reserve strategy if your revenue becomes more stable or your operating structure changes.
Cash reserves are part of financial resilience
Strong businesses don't only plan for growth.
They also plan for uncertainty.
Having sufficient cash available can give you more flexibility when opportunities arise or unexpected challenges occur.
It can also reduce the pressure to make poor decisions simply because the business needs cash immediately.
Understand your numbers before setting a target
Your accountant can help you assess your business's cash requirements by looking at factors such as profitability, working capital, debt, seasonal trends and projected cash flow.
At Affinity Accounting & Advisory Limited, we work with New Zealand business owners to understand their financial position and develop practical strategies for stronger business performance.
If you're unsure whether your business has an appropriate cash reserve, it may be time to review your numbers.
What our clients say
“Dylan is one of the best accountants I've worked with. He makes a point of explaining things as plainly as possible to those of us who don't understand accounting speak. He has a solid knowledge of best practices in the industry, but most importantly he will always recommend what is most suitable for your specific business. I will continue to recommend Dylan and Affinity Accounting to my clients when they are looking for an accountant.”
-Jay Brooker